Monday, 17 June 2024

BUY, REFURBISH & REFINANCE (BRR) STRATEGY - AN OVERVIEW

Buying refurbish refinance (BRR) properties in the UK can be a lucrative strategy for property investors looking to add value and increase rental yields or property value. 


Here’s a basic overview of how the process typically works:


1. BUY (ACQUISITION)


Location and Research: Identify areas with potential for growth or high rental demand. Research local property prices, rental yields, and market trends.


Finance: Secure financing through a buy-to-let mortgage or other suitable funding options. Factor in costs such as stamp duty, legal fees, and potential refurbishment expenses.


Purchase: Purchase a property below market value (BMV) if possible, considering potential refurbishment costs and the post-refurbishment value (PRV).


2. REFURBISH


Planning: Develop a refurbishment plan based on your budget and goals. Obtain necessary planning permissions and adhere to building regulations.


Execution: Carry out the refurbishment work, which may include structural changes, cosmetic upgrades, improving energy efficiency, and addressing any necessary repairs.


Quality Control: Ensure the work meets high standards to enhance the property's appeal and value.


3. REFINANCE


Revaluation: Once the refurbishment is complete, arrange for a professional property valuation to determine the new market value of the property (PRV).


Mortgage: Apply for a new mortgage based on the post-refurbishment value (PRV), typically aiming to release a significant portion of your initial investment (deposit and refurbishment costs) to use for further investments.


KEY CONSIDERATIONS:

Costs and Budgeting: Carefully estimate all costs involved, including purchase, refurbishment, legal fees, and ongoing expenses like property management and maintenance.


Market Knowledge: Stay informed about local property markets, rental demand, and regulations to make informed investment decisions.


Risk Management: Factor in potential risks such as delays in refurbishment, market fluctuations, and changes in interest rates.


Tax Implications: Consider tax implications such as stamp duty, capital gains tax, and income tax on rental income. Seek advice from a tax advisor to optimise your financial strategy.


Benefits:

Increased Yield: Improve rental income potential through higher-quality properties or increased rental demand.


Capital Growth: Enhance property value, allowing for potential equity growth over time.


Portfolio Expansion: Use released capital to invest in additional properties, expanding your portfolio.


Challenges:

Time and Effort: Refurbishment projects require time, effort, and management skills to oversee effectively.


Financial Risk: Investment in refurbishment and reliance on property valuation outcomes involve financial risk.


Market Conditions: Property market fluctuations can impact profitability and investment returns.


CONCLUSION:


Buying refurbish refinance (BRR) properties in the UK can be a viable strategy for investors with a thorough understanding of the market, access to financing, and the ability to manage refurbishment projects effectively. 


It combines elements of property acquisition, renovation, and financial management to maximise returns on investment through improved property value and rental income potential.


--------------------------------------------------------------------------------------------------
While every effort has been made to check the accuracy of this article, readers should always make their own checks.  

The Author does not accept any responsibility for misstatements made or any misunderstandings arising from it.

---------------------------------------------------------------------------------------------------

Sunday, 16 June 2024

HOW TO MAKE MONEY AT HOME

Please see below on some ideas on how you can earn some extra money at home.  Many see these as 'Side Hustles' to your main occupation and many of the below you can do part-time, some you may be able to do full-time.

  • AIR BNB - rent a room out at your home, or your house when you go on holiday.
  • RENT YOUR CAR PARKING SPACE - rent part of your drive.
(See our recent articles on the 1. AirBnb and . 2Renting a Car space for some useful information.)
  • WALK DOGS or  maybe give them a home when their owners go on holiday.
  • SELL THINGS ON EBAY AND AMAZON 
  • USE DAILY REWARDS - Look at your regular shops and see where you can save money
  • SELL CRAFTS ON ETSY
  • CREATE/ SELL ONLINE COURSES
  • TAKE ONLINE SURVEYS - watch your data on this one, do not share too much personal information.
  • START A BLOG - share your knowledge and expertise
  • BECOME A FREELANCE WRITER
  • BECOME A VIRTUAL ASSISTANT
  • DO DATA ENTRY JOBS
  • SELL YOUR PHOTOS
  • TEST WEBSITES
  • BUY AND SELL WEBSITES
  • TUTOR OTHERS ONLINE
  • TEACH ENGLISH ONLINE
  • DELIVER FOR UBER EATS
  • OFFER HANDYMAN SERVICES - Do DIY jobs for neighbours, e.g. Attend their gardens. do their shopping, mind their pets etc.

--------------------------------------------------------------------------------------------------
While every effort has been made to check the accuracy of this article, readers should always make their own checks.  

The Author does not accept any responsibility for misstatements made or any misunderstandings arising from it.
---------------------------------------------------------------------------------------------------

Saturday, 15 June 2024

WHAT PROPERTY CAN I AFFORD?

Determining what property you can afford involves evaluating several key factors, including your income, expenses, savings, and the cost of the property you are considering. 


Here's a step-by-step guide to help you figure out what property you can afford:


STEP 1: CALCULATE YOUR BUDGET


Income: Determine your monthly gross income (before taxes). Include all sources of income such as salary, bonuses, rental income, and any other earnings.

Debt-to-Income Ratio (DTI): This ratio compares your monthly debt payments to your gross monthly income. Lenders typically prefer a DTI ratio of 36% or lower. 

Calculate your current DTI ratio by adding up all your monthly debt payments (loans, credit card payments, etc.) and dividing by your gross monthly income.


Monthly Housing Budget: Financial advisors often suggest that your monthly housing expenses (including mortgage, insurance, taxes, and maintenance) should not exceed 28-30% of your gross monthly income.


STEP 2: ASSESS YOUR SAVINGS AND UPFRONT COST


Deposit: Aim for a deposit of at least 20% to avoid private mortgage insurance (PMI). However, some loans may allow lower deposit payments.


Closing Costs: Estimate closing costs at 2-5% of the property purchase price. These include fees for appraisal, title insurance, and legal services.


Emergency Fund: Maintain an emergency fund that covers 3-6 months of living expenses to manage unexpected financial situations.


STEP 3: DETERMINE YOUR MORTGAGE


Loan Term: Choose between different mortgage terms (e.g. 15-year vs. 30-year). A shorter term usually means higher monthly payments but less interest paid over the life of the loan.


Interest Rate: Shop around for the best mortgage rates. Your credit score, loan type, and deposit payment amount can influence the rate you receive.


Monthly Mortgage Payment: Use an online mortgage calculator to estimate your monthly mortgage payment, including principal, interest, property taxes, and insurance (PITI).


STEP 4: ESTIMATE AFFORDABILITY


Here’s a simplified formula to estimate the maximum home price you can afford:


Maximum Home Price = Annual Gross Income × 2.5


Maximum Home Price = Deposit Percentage


Annual Gross Income× 2.5

​———————————————————————————


For example, if your annual gross income is £60,000 and you have a 20% deposit:


Maximum Home Price = £60,000 × 2.5 : 0.20 = £300,000


Maximum Home Price = 0.20 : £60,000 × 2.5 =£300,000


STEP 5: ADJUST FOR LOCAL MARKET CONDITIONS


Real estate markets vary widely. Consider the cost of living and property prices in your desired location. You may need to adjust your expectations based on local market conditions.


Example Calculation;  Assume the following:

  • Gross annual income: £60,000
  • Monthly debt payments: £500
  • Desired DTI ratio: 36%
  • Deposit: 20%
  • Interest rate: 4%
  • Loan term: 30 years
  • Monthly Income: £60,000 / 12 = £5,000
  • Max. Monthly Housing Expense: £5,000 * 0.28 = £1,400

Monthly Mortgage Payment: 
Use an online mortgage calculator to determine how much home you can afford with a £1,400 monthly mortgage payment at a 4% interest rate over 30 years.


Using a mortgage calculator, you may find that a £1,400 monthly payment corresponds to a mortgage of approximately £250,000. 


Adding a 20% deposit, you could afford a property priced around £312,500.


CONCLUSION


Affording a property depends on various personal and financial factors. Carefully analyse your financial situation, use online tools to estimate costs, and consult with financial advisors or mortgage brokers to ensure you make a well-informed decision.

HOW TO BUILD A SHED: A COMPREHENSIVE GUIDE

Building a shed is a rewarding project that can provide extra storage space, a workshop, or even a small retreat. This guide will walk you through the steps to build a sturdy and functional shed, complete with sketches to illustrate the process.


PLANNING AND PREPARATION


  1. DETERMINE THE PURPOSE AND SIZE

Before you start, decide the primary purpose of your shed. This will help you determine the size and design features needed. Common sizes range from 6x8 feet for a small garden shed to 12x16 feet or larger for a workshop.


2. CHOOSE A LOCATION


Select a flat, well-drained area for your shed. Ensure it’s accessible and meets any local zoning regulations or homeowners' association rules.


3. GATHER MATERIALS AND TOOLS


Here’s a list of materials and tools you will need:


MATERIALS:

  • Pressure-treated lumber for the foundation
  • Framing lumber (2x4s)
  • Plywood or OSB for the floor and walls
  • Siding (T1-11, vinyl, or wood)
  • Roofing material (shingles or metal roofing)
  • Screws, nails, and wood glue
  • Doors and windows (optional)

TOOLS:

  • Tape measure
  • Level
  • Hammer or nail gun
  • Circular saw or miter saw
  • Drill
  • Square
  • Shovel
  • Ladder
  • Safety gear (gloves, goggles)

BUILDING THE SHED


STEP 1: BUILD THE FOUNDATION


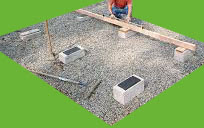
Here’s a basic sketch of the shed foundation layout.


  • Prepare the Site: Clear the area of debris and level the ground. Mark the shed's footprint using stakes and string.
  • Install the Foundation: There are several types of foundations you can use:
  • Concrete Blocks: Place concrete blocks at the corners and along the perimeter. Ensure they are level and spaced correctly.

  • Concrete Slab: Pour a concrete slab for a permanent foundation.

  • Wooden Skids: Use pressure-treated 4x4 or 4x6 skids for a movable foundation.


STEP 2: BUILD THE FLOOR FRAME


Floor framing layout.

  • Construct the Floor Frame: Use 2x6 or 2x8 lumber to create a frame that fits the shed’s dimensions. Space the joists 16 inches apart and secure them with nails or screws.
  • Attach the Floor: Cover the frame with ¾-inch plywood or OSB, securing it with screws.


STEP 3: BUILD THE WALLS


Wall framing layout.

  • Construct the Wall Frames: Build the wall frames using 2x4 lumber. Ensure the frames are square and the studs are spaced 16 inches apart.
  • Install the Walls: Erect the wall frames one at a time, securing them to the floor and to each other at the corners. Use temporary braces to hold the walls in place.


STEP 4: ADD SIDINGS AND WINDOWS


Wall with siding and window placement.

  • Attach Siding: Install your chosen siding material (T1-11, vinyl, or wood) to the wall frames. Make sure to cut out openings for windows and doors.
  • Install Windows and Doors: Fit windows and doors into the pre-cut openings, securing them with screws and caulking around the edges to seal them.


STEP 5: BUILD THE ROOF


Roof framing and layout.

  • Construct the Roof Frame: Build the roof trusses or rafters using 2x4 lumber. Ensure they are evenly spaced and secure them to the top plates of the wall frames.
  • Attach the Roof Sheathing: Cover the roof frame with plywood or OSB, securing it with screws.
  • Install Roofing Material: Apply roofing felt, then install shingles or metal roofing according to the manufacturer’s instructions.


STEP 6: FINISH THE SHED


Completed shed with all components.

  • Add Trim and Paint: Install trim around doors, windows, and corners. Paint or stain the shed to protect it from the elements and enhance its appearance.
  • Install Flooring (Optional): If desired, install additional flooring material like vinyl or laminate inside the shed.


TIPS FOR A SUCCESSFUL SHED BUILD


  • Follow Local Codes: Ensure your shed complies with local building codes and obtain any necessary permits.
  • Quality Materials: Use high-quality, pressure-treated lumber and weather-resistant materials to ensure your shed's longevity.
  • Accurate Measurements: Double-check all measurements and use a level to keep everything straight and square.
  • Safety First: Wear appropriate safety gear and work cautiously, especially when using power tools and working at heights.


Building a shed is a manageable project for most DIY enthusiasts and can be a valuable addition to your property. With careful planning, the right materials, and attention to detail, you can create a shed that meets your needs and stands the test of time.


😁 Happy building! 😁


————————————————————————————

While every effort has been made to check the accuracy of this article, readers should always make their own checks.


The Author does not accept any responsibility for misstatements made or any misunderstandings arising from the information provided.

————————————————————————————

DO I REQUIRE PLANNING PERMISSION?

Whether you need planning permission in the UK depends on the type of work you plan to carry out. Here are the key considerations: Permitted...