Showing posts with label Project manger. Show all posts

Sunday, 16 June 2024

HOW TO MAKE MONEY AT HOME

Please see below on some ideas on how you can earn some extra money at home.  Many see these as 'Side Hustles' to your main occupation and many of the below you can do part-time, some you may be able to do full-time.

  • AIR BNB - rent a room out at your home, or your house when you go on holiday.
  • RENT YOUR CAR PARKING SPACE - rent part of your drive.
(See our recent articles on the 1. AirBnb and . 2Renting a Car space for some useful information.)
  • WALK DOGS or  maybe give them a home when their owners go on holiday.
  • SELL THINGS ON EBAY AND AMAZON 
  • USE DAILY REWARDS - Look at your regular shops and see where you can save money
  • SELL CRAFTS ON ETSY
  • CREATE/ SELL ONLINE COURSES
  • TAKE ONLINE SURVEYS - watch your data on this one, do not share too much personal information.
  • START A BLOG - share your knowledge and expertise
  • BECOME A FREELANCE WRITER
  • BECOME A VIRTUAL ASSISTANT
  • DO DATA ENTRY JOBS
  • SELL YOUR PHOTOS
  • TEST WEBSITES
  • BUY AND SELL WEBSITES
  • TUTOR OTHERS ONLINE
  • TEACH ENGLISH ONLINE
  • DELIVER FOR UBER EATS
  • OFFER HANDYMAN SERVICES - Do DIY jobs for neighbours, e.g. Attend their gardens. do their shopping, mind their pets etc.

--------------------------------------------------------------------------------------------------
While every effort has been made to check the accuracy of this article, readers should always make their own checks.  

The Author does not accept any responsibility for misstatements made or any misunderstandings arising from it.
---------------------------------------------------------------------------------------------------

Saturday, 15 June 2024

WHAT PROPERTY CAN I AFFORD?

Determining what property you can afford involves evaluating several key factors, including your income, expenses, savings, and the cost of the property you are considering. 


Here's a step-by-step guide to help you figure out what property you can afford:


STEP 1: CALCULATE YOUR BUDGET


Income: Determine your monthly gross income (before taxes). Include all sources of income such as salary, bonuses, rental income, and any other earnings.

Debt-to-Income Ratio (DTI): This ratio compares your monthly debt payments to your gross monthly income. Lenders typically prefer a DTI ratio of 36% or lower. 

Calculate your current DTI ratio by adding up all your monthly debt payments (loans, credit card payments, etc.) and dividing by your gross monthly income.


Monthly Housing Budget: Financial advisors often suggest that your monthly housing expenses (including mortgage, insurance, taxes, and maintenance) should not exceed 28-30% of your gross monthly income.


STEP 2: ASSESS YOUR SAVINGS AND UPFRONT COST


Deposit: Aim for a deposit of at least 20% to avoid private mortgage insurance (PMI). However, some loans may allow lower deposit payments.


Closing Costs: Estimate closing costs at 2-5% of the property purchase price. These include fees for appraisal, title insurance, and legal services.


Emergency Fund: Maintain an emergency fund that covers 3-6 months of living expenses to manage unexpected financial situations.


STEP 3: DETERMINE YOUR MORTGAGE


Loan Term: Choose between different mortgage terms (e.g. 15-year vs. 30-year). A shorter term usually means higher monthly payments but less interest paid over the life of the loan.


Interest Rate: Shop around for the best mortgage rates. Your credit score, loan type, and deposit payment amount can influence the rate you receive.


Monthly Mortgage Payment: Use an online mortgage calculator to estimate your monthly mortgage payment, including principal, interest, property taxes, and insurance (PITI).


STEP 4: ESTIMATE AFFORDABILITY


Here’s a simplified formula to estimate the maximum home price you can afford:


Maximum Home Price = Annual Gross Income × 2.5


Maximum Home Price = Deposit Percentage


Annual Gross Income× 2.5

​———————————————————————————


For example, if your annual gross income is £60,000 and you have a 20% deposit:


Maximum Home Price = £60,000 × 2.5 : 0.20 = £300,000


Maximum Home Price = 0.20 : £60,000 × 2.5 =£300,000


STEP 5: ADJUST FOR LOCAL MARKET CONDITIONS


Real estate markets vary widely. Consider the cost of living and property prices in your desired location. You may need to adjust your expectations based on local market conditions.


Example Calculation;  Assume the following:

  • Gross annual income: £60,000
  • Monthly debt payments: £500
  • Desired DTI ratio: 36%
  • Deposit: 20%
  • Interest rate: 4%
  • Loan term: 30 years
  • Monthly Income: £60,000 / 12 = £5,000
  • Max. Monthly Housing Expense: £5,000 * 0.28 = £1,400

Monthly Mortgage Payment: 
Use an online mortgage calculator to determine how much home you can afford with a £1,400 monthly mortgage payment at a 4% interest rate over 30 years.


Using a mortgage calculator, you may find that a £1,400 monthly payment corresponds to a mortgage of approximately £250,000. 


Adding a 20% deposit, you could afford a property priced around £312,500.


CONCLUSION


Affording a property depends on various personal and financial factors. Carefully analyse your financial situation, use online tools to estimate costs, and consult with financial advisors or mortgage brokers to ensure you make a well-informed decision.

HOW TO BUILD A SHED: A COMPREHENSIVE GUIDE

Building a shed is a rewarding project that can provide extra storage space, a workshop, or even a small retreat. This guide will walk you through the steps to build a sturdy and functional shed, complete with sketches to illustrate the process.


PLANNING AND PREPARATION


  1. DETERMINE THE PURPOSE AND SIZE

Before you start, decide the primary purpose of your shed. This will help you determine the size and design features needed. Common sizes range from 6x8 feet for a small garden shed to 12x16 feet or larger for a workshop.


2. CHOOSE A LOCATION


Select a flat, well-drained area for your shed. Ensure it’s accessible and meets any local zoning regulations or homeowners' association rules.


3. GATHER MATERIALS AND TOOLS


Here’s a list of materials and tools you will need:


MATERIALS:

  • Pressure-treated lumber for the foundation
  • Framing lumber (2x4s)
  • Plywood or OSB for the floor and walls
  • Siding (T1-11, vinyl, or wood)
  • Roofing material (shingles or metal roofing)
  • Screws, nails, and wood glue
  • Doors and windows (optional)

TOOLS:

  • Tape measure
  • Level
  • Hammer or nail gun
  • Circular saw or miter saw
  • Drill
  • Square
  • Shovel
  • Ladder
  • Safety gear (gloves, goggles)

BUILDING THE SHED


STEP 1: BUILD THE FOUNDATION


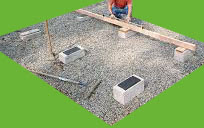
Here’s a basic sketch of the shed foundation layout.


  • Prepare the Site: Clear the area of debris and level the ground. Mark the shed's footprint using stakes and string.
  • Install the Foundation: There are several types of foundations you can use:
  • Concrete Blocks: Place concrete blocks at the corners and along the perimeter. Ensure they are level and spaced correctly.

  • Concrete Slab: Pour a concrete slab for a permanent foundation.

  • Wooden Skids: Use pressure-treated 4x4 or 4x6 skids for a movable foundation.


STEP 2: BUILD THE FLOOR FRAME


Floor framing layout.

  • Construct the Floor Frame: Use 2x6 or 2x8 lumber to create a frame that fits the shed’s dimensions. Space the joists 16 inches apart and secure them with nails or screws.
  • Attach the Floor: Cover the frame with ¾-inch plywood or OSB, securing it with screws.


STEP 3: BUILD THE WALLS


Wall framing layout.

  • Construct the Wall Frames: Build the wall frames using 2x4 lumber. Ensure the frames are square and the studs are spaced 16 inches apart.
  • Install the Walls: Erect the wall frames one at a time, securing them to the floor and to each other at the corners. Use temporary braces to hold the walls in place.


STEP 4: ADD SIDINGS AND WINDOWS


Wall with siding and window placement.

  • Attach Siding: Install your chosen siding material (T1-11, vinyl, or wood) to the wall frames. Make sure to cut out openings for windows and doors.
  • Install Windows and Doors: Fit windows and doors into the pre-cut openings, securing them with screws and caulking around the edges to seal them.


STEP 5: BUILD THE ROOF


Roof framing and layout.

  • Construct the Roof Frame: Build the roof trusses or rafters using 2x4 lumber. Ensure they are evenly spaced and secure them to the top plates of the wall frames.
  • Attach the Roof Sheathing: Cover the roof frame with plywood or OSB, securing it with screws.
  • Install Roofing Material: Apply roofing felt, then install shingles or metal roofing according to the manufacturer’s instructions.


STEP 6: FINISH THE SHED


Completed shed with all components.

  • Add Trim and Paint: Install trim around doors, windows, and corners. Paint or stain the shed to protect it from the elements and enhance its appearance.
  • Install Flooring (Optional): If desired, install additional flooring material like vinyl or laminate inside the shed.


TIPS FOR A SUCCESSFUL SHED BUILD


  • Follow Local Codes: Ensure your shed complies with local building codes and obtain any necessary permits.
  • Quality Materials: Use high-quality, pressure-treated lumber and weather-resistant materials to ensure your shed's longevity.
  • Accurate Measurements: Double-check all measurements and use a level to keep everything straight and square.
  • Safety First: Wear appropriate safety gear and work cautiously, especially when using power tools and working at heights.


Building a shed is a manageable project for most DIY enthusiasts and can be a valuable addition to your property. With careful planning, the right materials, and attention to detail, you can create a shed that meets your needs and stands the test of time.


😁 Happy building! 😁


————————————————————————————

While every effort has been made to check the accuracy of this article, readers should always make their own checks.


The Author does not accept any responsibility for misstatements made or any misunderstandings arising from the information provided.

————————————————————————————

Monday, 10 June 2024

SHOULD YOU MOVE OR IMPROVE YOUR HOME? WEIGHING THE PROS AND CONS


Deciding whether to move to a new home or invest in improving your current one is a significant decision that involves various considerations. 
Both options come with their own set of advantages, disadvantages, and costs. 

Here’s a comprehensive look at the factors to consider when deciding whether to move or improve.


MOVING TO A NEW HOME


ADVANTAGES

  • New Opportunities: Moving to a new home can offer access to better job prospects, schools, amenities, and an overall improved quality of life. If your current area no longer meets your needs, relocating can provide a fresh start.
  • Better Fit: A new home can be tailored to your current lifestyle and future needs. Whether it’s more space for a growing family, a different layout, or a location closer to work, a new home can offer features that your current home cannot.
  • Modern Amenities: New homes often come with modern features and energy-efficient systems, reducing future maintenance costs and utility bills. This can lead to a more comfortable and cost-effective living environment.
  • Investment Potential: Moving to an area with rising property values can be a smart investment, potentially increasing your home's value over time.

DISADVANTAGES

  • High Costs: Moving involves significant expenses, including estate agent fees, legal fees, stamp duty (in the UK), removal costs, and potential renovations to prepare your home for sale. These costs can quickly add up, often reaching tens of thousands of pounds.
  • Emotional Stress: Leaving a familiar environment, neighbours, and routines can be emotionally taxing. Adjusting to a new area and building a new social network takes time and effort.
  • Uncertainty: The process of buying and selling a home is fraught with uncertainties. Market conditions, the timing of transactions, and potential complications during the sale or purchase can create stress and delays.
  • Market Dependency: The success of selling your current home depends on the property market. If the market is slow or values are declining, you might have to sell for less than expected or wait longer to find a buyer.


IMPROVING YOUR HOME


ADVANTAGES

  • Cost Efficiency: Home improvements can be more cost-effective than moving. Instead of incurring all the costs associated with buying a new home, you can invest in upgrading your current property to better suit your needs.
  • Personalisation: Renovating allows you to tailor your home to your specific tastes and requirements. Whether it’s adding an extension, modernising the kitchen, or creating an open-plan living space, improvements can make your home more functional and enjoyable.
  • Increased Property Value: Strategic improvements can increase the value of your home, potentially providing a good return on investment when you eventually decide to sell.
  • Stability: Staying in your current home means you can maintain your social connections, children’s schooling, and familiarity with the neighbourhood, reducing the upheaval associated with moving.


DISAVANTGES

  • Disruption: Home improvements can be disruptive and stressful. Living through construction work can be noisy, messy, and inconvenient, sometimes requiring temporary relocation.
  • Unexpected Costs: Renovations often come with unexpected costs due to unforeseen issues such as structural problems or delays. Budget overruns are common, so it's essential to plan for contingencies.
  • Limited Space: There’s only so much you can do to expand or improve your current property. If the fundamental size or layout doesn’t meet your needs, no amount of renovation will solve this problem.
  • Planning and Permissions: Significant home improvements often require planning permission and adherence to building regulations. This can involve a lengthy and bureaucratic process, with no guarantee of approval.


COST-COMPARISON


MOVING COSTS

  • Estate Agent Fees: Typically 1-3% of the sale price.
  • Legal Fees: Around £1,000 - £3,000.
  • Stamp Duty: Variable, depending on the property's value and location.
  • Removal Costs: Approximately £300 - £1,500 depending on distance and amount of belongings.
  • Mortgage Fees: Can include arrangement fees, valuation fees, and potential early repayment charges on your current mortgage.


HOME IMPROVEMENT COSTS

  • Extension: Costs can range from £1,000 to £2,000 per square metre.
  • Kitchen Renovation: Typically £5,000 - £20,000.
  • Bathroom Renovation: Usually £3,000 - £10,000.
  • Loft Conversion: Around £20,000 - £50,000.
  • General Updates (painting, flooring, etc.): £1,000 - £5,000.


CONCLUSION


Both moving and improving your home have their merits and challenges. The decision ultimately depends on your personal circumstances, financial situation, and long-term goals. If your current location and property can be modified to meet your needs, home improvements might be the way to go. 

However, if you’re seeking significant lifestyle changes or your current home cannot be adapted, moving may be the better option.

Careful consideration of all factors, including the emotional and financial implications, is crucial. Consulting with real estate professionals, financial advisors, and builders can provide valuable insights and help you make an informed decision that best suits your needs and aspirations.

————————————————————————————

While every effort has been made to check the accuracy of this article, readers should always make their own checks.


The Author does not accept any responsibility for misstatements made or any misunderstandings arising from the information provided.

————————————————————————————

DO I REQUIRE PLANNING PERMISSION?

Whether you need planning permission in the UK depends on the type of work you plan to carry out. Here are the key considerations: Permitted...